What Is a New Home Construction Loan Calculator?
A New Home Construction Loan Calculator estimates the monthly payment, total interest, and repayment cost of financing a new home build based on the loan amount, interest rate, and loan term.
The calculator uses standard amortization math. You input:
- Total project cost (land + construction)
- Down payment
- Amount financed
- Annual interest rate
- Loan term
- Fees, where supported
The result is an estimate, not an official lender quote. Actual terms depend on your credit profile, project details, and lender policies.
New Home Construction Loan Calculator
Estimate your construction loan amount, construction-phase interest, permanent mortgage payment, and total financing cost.
Total Project Cost = Land Cost + Construction Cost + Other Project Costs
Construction Loan = Total Project Cost − Down Payment
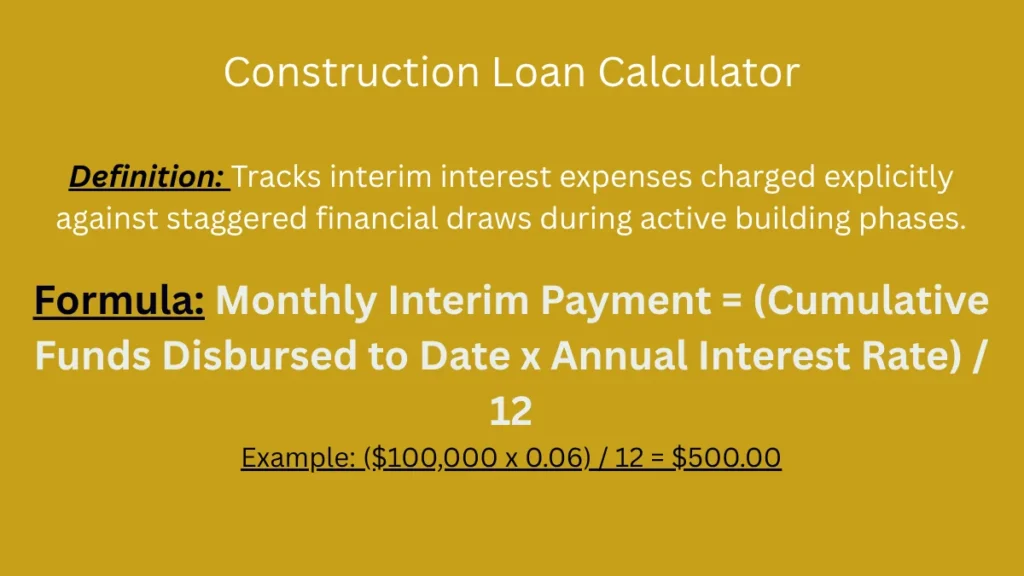
Estimated construction interest
Average Construction Balance = Construction Loan × 50%
Monthly Construction Interest = Average Construction Balance × Construction Rate ÷ 12
Estimated Construction Interest = Monthly Construction Interest × Construction Period
Permanent mortgage calculation
Monthly Payment = P × [r(1 + r)n] ÷ [(1 + r)n − 1]
where P is the construction loan balance, r is the monthly mortgage interest rate, and n is the total number of monthly payments.
Permanent Mortgage Interest
Total Permanent Payments − Construction Loan Amount
How Does a New Home Construction Loan Calculator Work?
The calculator performs a standard amortizing loan calculation. Each payment covers both interest and principal. Early payments are mostly interest; later payments are mostly principal.
For a construction loan, the calculation is more complex than a standard mortgage. Construction financing often involves staged draws, interest-only payments during the build, and conversion to permanent financing. A calculator may simplify these details or provide separate estimates for the construction period and the permanent loan.
Construction Loan Formula
The standard fixed-rate loan payment formula is:
M = P × [r(1 + r)^n] ÷ [(1 + r)^n − 1]
Where:
- M = periodic payment
- P = principal or amount financed
- r = periodic interest rate
- n = total number of payments
For monthly calculations:
Monthly Interest Rate = Annual Interest Rate ÷ 12
Number of Monthly Payments = Loan Term in Years × 12
This standard amortization formula may not exactly represent every construction loan. Construction financing can involve staged draws, interest-only periods, variable rates, fees, or conversion into permanent financing.
What Information Do You Need?
Land Price: The cost of the lot if you are purchasing it as part of the project. If you already own the land, its value may count as equity.
Construction Cost: The cost to build the home, including materials, labor, and contractor fees.
Total Project Cost: Land Price + Construction Cost + Other Eligible Costs.
Down Payment: The amount paid upfront. Construction loans often require larger down payments than standard mortgages.
Loan Amount: Total Project Cost − Down Payment.
Interest Rate: The annual percentage charged by the lender. Construction loan rates are often higher than permanent mortgage rates.
Loan Term: The repayment period. This may include a construction period (typically 6–24 months) plus a permanent loan term.
Construction Period: The expected time to complete the build.
Loan Fees: Origination, documentation, or construction administration fees.
Closing Costs: Fees paid at closing, typically 2%–5% of the loan amount.
Contingency Amount: A reserve for unexpected costs, often 5%–10% of construction costs.
Permanent Mortgage Information: Terms for the loan after construction converts.
New Home Construction Loan Example
Illustrative Scenario:
- Construction and project cost: $350,000
- Down payment: $70,000
- Amount financed: $280,000
- Interest rate: 8%
- Loan term: 30 years
Monthly rate: 0.08 ÷ 12 = 0.006667
Number of payments: 30 × 12 = 360
M = 280,000 × [0.006667 × (1.006667)^360] ÷ [(1.006667)^360 − 1]
M ≈ $2,054.36
Total paid: $2,054.36 × 360 = $739,569.60
Estimated total interest: $739,569.60 − $280,000 = $459,569.60
This example shows the permanent mortgage payment after construction. During the construction period, payments may be interest-only on drawn amounts.
How Construction Loan Interest Works
Construction loan interest is often calculated differently from a standard mortgage. Key points:
- Interest on drawn amounts: Interest may be charged only on the amount actually drawn, not the full approved loan amount.
- Staged draws: Funds are released in stages as construction progresses.
- Construction-period interest: Payments may be interest-only during the build.
- Full loan balance vs. outstanding balance: The permanent loan is based on the full amount, but construction interest applies to the outstanding balance.
- Permanent mortgage conversion: The loan may convert to a standard mortgage after construction.
Terms vary by lender and loan product. Not every construction loan charges interest only on drawn funds.
Construction Loan vs. Regular Mortgage
| Feature | Construction Loan | Traditional Mortgage |
|---|---|---|
| Purpose | Finance building a new home | Purchase an existing home |
| When funds provided | In stages as construction progresses | Lump sum at closing |
| Payment structure | Interest-only during construction; converts to amortizing | Fully amortizing from start |
| Interest calculation | Often on drawn amounts during construction | On full loan balance |
| Construction period | Typically 6–24 months | Not applicable |
| Underwriting | Evaluates project plans, builder, and borrower | Evaluates property and borrower |
| Inspections/draws | Required before each disbursement | Not applicable |
| Repayment | Short-term or converts to permanent | Long-term (15–30 years) |
| Conversion | May convert to permanent financing | Not applicable |
Some borrowers use a construction-to-permanent loan (one loan, one closing) while others use separate financing.
What Does a Construction Loan Cover?
Potential project costs include:
- Land purchase
- Site preparation
- Foundation, framing, roofing
- Plumbing, electrical, HVAC
- Insulation, windows, doors
- Interior finishes
- Labor and materials
- Permits and inspections
- Architectural or engineering fees
- Contingency reserves
Eligible expenses vary by lender and loan product.
How Much Down Payment Is Needed?
There is no universal down-payment requirement. Typical construction loan down payments range from 10% to 25% of total project cost, with many lenders expecting around 20%.
Factors that affect the required down payment:
- Loan type
- Lender
- Borrower credit
- Project cost
- Land ownership
- Loan-to-value
- Completed property value
- Borrower finances
- Construction experience
A larger down payment reduces the amount financed and can reduce interest costs.
How Does the Down Payment Change the Payment?
Project cost: $400,000 | Rate: 8% | Term: 30 years
| Down Payment | Amount Financed | Monthly Payment | Total Interest |
|---|---|---|---|
| $40,000 | $360,000 | $2,641.63 | $590,986.80 |
| $80,000 | $320,000 | $2,347.90 | $525,244.00 |
| $120,000 | $280,000 | $2,054.36 | $459,569.60 |
A larger down payment reduces the monthly payment and total interest.
How Does the Interest Rate Affect a Construction Loan?
Amount financed: $300,000 | Term: 30 years
| Rate | Monthly Payment | Total Interest |
|---|---|---|
| 6% | $1,798.65 | $347,514.00 |
| 7% | $1,995.91 | $418,527.60 |
| 8% | $2,201.29 | $492,464.40 |
| 9% | $2,413.96 | $569,025.60 |
Higher rates increase both the monthly payment and total interest. Construction loan rates are often higher than permanent mortgage rates.
How Does the Loan Term Affect Total Cost?
Amount financed: $280,000 | Rate: 8%
| Term | Monthly Payment | Total Interest |
|---|---|---|
| 15 years | $2,676.18 | $201,712.40 |
| 20 years | $2,342.02 | $282,084.80 |
| 25 years | $2,160.99 | $368,297.00 |
| 30 years | $2,054.36 | $459,569.60 |
Shorter terms mean higher monthly payments but less total interest. Longer terms mean lower monthly payments but more total interest.
Construction Loan Payment vs. Total Project Cost
The monthly loan payment is only one part of the total cost of building a home. Other costs include:
- Land cost
- Down payment
- Interest
- Lender fees
- Closing costs
- Permits
- Professional fees
- Contingency funds
- Taxes
- Insurance
Budget for all costs, not just the loan payment.
Construction Loan Draw Schedule
Construction draws are staged releases of funds as construction progresses. Typical stages include:
- Foundation
- Framing
- Roofing
- Mechanical systems
- Interior work
- Completion
Exact draw schedules and inspection requirements vary by lender. Lenders often require inspections before each disbursement.
What Affects Construction Loan Cost?
- Project cost
- Loan amount
- Down payment
- Interest rate
- Loan term
- Construction period
- Draw schedule
- Lender fees
- Closing costs
- Credit profile
- Property value
- Land ownership
- Loan-to-value
- Loan structure
- Permanent financing terms
New Construction Loan vs. Construction-to-Permanent Loan
| Feature | Standalone Construction Loan | Construction-to-Permanent Loan |
|---|---|---|
| Closings | Two (construction + permanent) | One |
| Closing costs | Two sets | One set |
| Conversion | Reapply for permanent mortgage | Automatic conversion |
| Rate | May be higher | Often lower |
| Typical use | Custom builds, some lenders | Common for primary residences |
Construction-to-permanent loans consolidate financing into one loan with one closing. The single-close structure has been growing in adoption.
New Home Construction Loan for Land You Already Own
If you own the land, its equity may count toward your down payment or reduce the amount financed. Lenders may allow land equity to substitute for some cash down payment.
However, land equity does not automatically eliminate a down payment. Lenders still evaluate the project and borrower.
How to Use the New Home Construction Loan Calculator
- Enter the estimated project cost.
- Enter the land cost if applicable.
- Enter the planned down payment.
- Calculate the estimated amount financed.
- Enter the interest rate.
- Enter the loan term.
- Enter fees or other supported costs.
- Click Calculate.
- Review the estimated payment.
- Review total interest and total repayment.
- Compare different down-payment scenarios.
- Compare different interest rates and loan terms.
- Compare the calculator estimate with actual lender terms.
How to Reduce Construction Financing Costs
- Compare multiple financing offers
- Understand the complete fee structure
- Compare total borrowing cost rather than only monthly payment
- Consider an appropriate down payment
- Improve credit where possible
- Control unnecessary project costs
- Maintain a realistic contingency reserve
- Compare loan terms
- Understand construction-period interest
- Review conversion terms
- Avoid financing unnecessary costs
These are general strategies, not personalized financial advice.
Costs Beyond the Construction Loan
- Land
- Permits
- Architectural fees
- Engineering
- Surveys
- Site preparation
- Utility connections
- Inspections
- Insurance
- Property taxes
- Landscaping
- Appliances
- Flooring
- Cabinetry
- Fixtures
- Driveway
- Contingency funds
- Temporary housing
- Financing and closing costs
Closing costs on new construction typically range from 2% to 5% of the home’s purchase price.
How Accurate Is a New Home Construction Loan Calculator?
The calculator provides an estimate. Actual financing may differ because of:
- Lender underwriting
- Credit profile
- Loan structure
- Interest rate
- Staged draws
- Fees
- Closing costs
- Taxes
- Insurance
- Property valuation
- Construction timeline
- Permanent financing terms
- Payment timing
The calculator is not a lender approval or financing offer.
Common Construction Loan Calculator Mistakes
- Entering the wrong project cost
- Forgetting land costs
- Confusing down payment with amount financed
- Ignoring construction-period interest
- Using the wrong interest rate
- Choosing a loan term without checking total interest
- Ignoring lender fees
- Ignoring closing costs
- Forgetting contingency funds
- Focusing only on monthly payment
- Assuming the calculator equals a lender quote
- Ignoring permanent mortgage terms
- Underestimating construction costs
When Is a New Home Construction Loan Calculator Most Useful?
- Planning a new home
- Estimating affordability
- Comparing down payments
- Comparing loan terms
- Evaluating construction budgets
- Preparing for lender conversations
- Comparing financing scenarios
- Estimating long-term borrowing costs
Construction Financing Comparison Table
| Project Cost | Down Payment | Amount Financed | Rate | Term | Estimated Payment | Total Interest |
|---|---|---|---|---|---|---|
| $300,000 | $60,000 | $240,000 | 8% | 30 yr | $1,760.85 | $393,906.00 |
| $400,000 | $80,000 | $320,000 | 8% | 30 yr | $2,347.90 | $525,244.00 |
| $500,000 | $100,000 | $400,000 | 8% | 30 yr | $2,934.82 | $656,535.20 |
These are illustrative examples, not lender quotes.
Commercial vs. Residential Construction Financing
A New Home Construction Loan Calculator is intended for residential home-building scenarios. Commercial construction financing can have different underwriting, terms, costs, and structures.
Related Calculators and Tools
- Construction Loan Calculator: A broader tool for construction financing scenarios.
- HELOC Payment Calculator: Helps estimate payments if you use a home equity line of credit alongside construction financing.
- Commercial Mortgage Calculator: Useful for comparing permanent mortgage payments with amortization schedules.
Frequently Asked Questions
What is a New Home Construction Loan Calculator?
A New Home Construction Loan Calculator estimates the monthly payment, total interest, and repayment cost of financing a new home build based on the loan amount, interest rate, and loan term.
How do you calculate a construction loan payment?
Use the amortization formula: M = P × [r(1 + r)^n] ÷ [(1 + r)^n − 1], where P is principal, r is monthly rate, and n is number of payments.
How much is the monthly payment on a construction loan?
It depends on the loan amount, rate, and term. A $280,000 loan at 8% for 30 years is approximately $2,054.36 per month.
How much down payment is needed for a construction loan?
Typical down payments range from 10% to 25%, with many lenders expecting around 20%.
How does interest work on a construction loan?
Interest may be charged only on the amount drawn during construction, not the full approved loan amount. Payments are often interest-only during the build.
Can I use a construction loan to build a new home?
Yes. Construction loans are designed to finance building or rehabilitating a home.
How long does a construction loan last?
Construction periods typically last 6–24 months, after which the loan may convert to a permanent mortgage or be paid off.
What affects construction loan interest rates?
Credit score, down payment, loan structure, lender, and market conditions all affect rates. Construction loan rates are generally higher than permanent mortgage rates.
What is the difference between a construction loan and a mortgage?
A construction loan is short-term and funds are drawn in stages. A mortgage is a long-term loan for purchasing an existing home.
What is a construction-to-permanent loan?
A construction-to-permanent loan combines construction financing and permanent mortgage into one loan with one closing.
Can I use land I already own toward a construction loan?
Yes. Land equity may count toward your down payment or reduce the amount financed.
Does a construction loan cover land?
It can, if the land purchase is part of the project. Some borrowers use separate financing for land.
Can construction loan costs be included in the financing?
Some costs may be financed, depending on the lender and loan structure. Fees and closing costs may need to be paid separately.
Are construction loan payments interest-only?
Payments are often interest-only during the construction period, then convert to amortizing payments after construction.
How accurate is a construction loan calculator?
It provides an estimate based on the inputs you supply. Actual lender offers may differ due to credit, fees, and lender-specific terms.
Summary
A New Home Construction Loan Calculator estimates your monthly payment, total interest, and overall financing cost for building a home. It uses the standard amortization formula to show how the amount financed, interest rate, and loan term affect what you pay.
The most important inputs are total project cost, down payment, interest rate, and loan term. A larger down payment reduces both the monthly payment and total interest. A higher interest rate increases both.
Construction-period financing can differ from a normal mortgage because funds are released in stages and payments may be interest-only. Calculator results are estimates, not lender offers. Compare multiple financing scenarios and lender terms before making a decision.