What Is a Commercial Mortgage Calculator?
It’s a simple tool that tells you what you’ll really pay on a commercial property loan. Monthly payments. Total interest. And the balloon payment that catches most people off guard.
Commercial loans aren’t like home loans. The terms are shorter. You need more cash upfront. And there’s usually a big payment due at the end. This calculator shows you all that before you sign anything.
Commercial Mortgage Calculator & Payment Schedule
Commercial Mortgage Results
Calculation Details
Monthly Payment Schedule
| Payment # | Beginning Balance | Payment | Principal | Interest | Ending Balance |
|---|
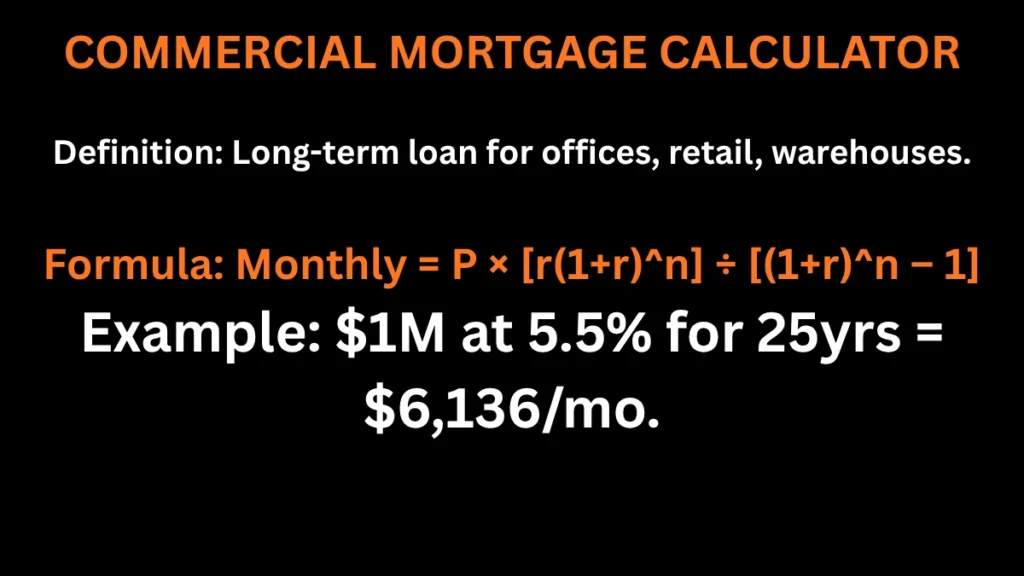
Commercial Mortgage Calculator & Payment Schedule
A commercial mortgage calculator estimates the cost of financing commercial property. Enter a few inputs—purchase price, down payment, interest rate, loan term, and amortization period—and the calculator estimates monthly principal and interest, annual debt service, total interest, and any potential balloon balance.
It also produces a payment schedule showing how each payment splits between principal and interest over time. The result is an estimate, not a lender quote. Actual commercial mortgage rates, fees, and terms vary by lender and property.
This article explains how the calculator works, the payment formula, loan term versus amortization, balloon payments, LTV, and how to compare financing options.
What Is a Commercial Mortgage Calculator?
A commercial mortgage calculator is a tool that estimates the payment and cost of a commercial property loan. It can calculate:
- Loan amount
- Monthly principal and interest
- Total monthly property payment (when taxes and insurance are included)
- Annual debt service
- Total mortgage interest
- Loan-to-value (LTV)
- Potential balloon balance
- Monthly payment schedule
It's used by business owners, commercial property investors, landlords, and developers who want to understand financing costs before applying. A commercial loan calculator helps answer a practical question: what will this loan cost per month, and can the property's income support it?
Most calculators require:
- Property purchase price
- Down payment
- Loan amount
- Interest rate
- Loan term
- Amortization period
- Property taxes, insurance, and other costs (optional)
An online calculator provides an estimate. A lender provides a quote. The quote is what determines the actual loan terms.
How Does a Commercial Mortgage Calculator Work?
The calculator applies a formula to your inputs. Each input affects the result.
Property purchase price. A higher price increases the loan amount and monthly payment.
Down payment. A larger down payment reduces the loan amount, lowering the monthly payment and LTV.
Loan amount. The purchase price minus down payment. It determines the payment and total interest.
Interest rate. A higher rate increases the monthly payment, annual debt service, and total interest.
Loan term. How long the loan remains outstanding before maturity. A shorter term may result in a balloon balance.
Amortization period. The period used to calculate scheduled payments. A longer amortization reduces the monthly payment but increases total interest.
Property taxes. Often added to the monthly payment when escrowed.
Insurance. Property insurance is a recurring cost that may be included in the monthly payment.
Maintenance and HOA or association fees. These affect total monthly property costs but may not be part of the mortgage payment itself.
Changing any input changes the output. Running multiple scenarios gives a clearer picture than a single estimate.
Commercial Mortgage Payment Formula
The standard formula for a fixed-rate, fully amortizing payment is:
M = P × [r(1+r)^n] / [(1+r)^n − 1]
Where:
- M = monthly principal and interest payment
- P = loan principal
- r = monthly interest rate
- n = total number of monthly payments
To convert:
Monthly interest rate = Annual interest rate ÷ 12 ÷ 100
Number of payments = Amortization period × 12
If the interest rate is zero, the formula simplifies:
Monthly payment = Loan amount ÷ number of payments
This formula assumes a fixed rate and fully amortizing structure. Many commercial mortgages use different structures, including:
- Variable rates
- Interest-only periods
- Balloon payments
- Shorter loan terms than amortization periods
- Lender fees and closing costs
Not every commercial mortgage follows the standard amortization formula. The formula estimates; the loan agreement determines the actual payment.
How to Calculate a Commercial Mortgage Payment
Here's a hypothetical example using the standard formula.
Inputs:
- Property purchase price: $1,000,000
- Down payment: $300,000
- Loan amount: $700,000
- Annual interest rate: 7%
- Amortization period: 25 years (300 months)
- Loan term: 10 years
Step 1: Convert the annual rate to a monthly rate.
7% ÷ 12 ÷ 100 = 0.005833 per month
Step 2: Determine the number of payments.
25 years × 12 = 300 monthly payments
Step 3: Apply the formula.
M = 700,000 × [0.005833(1.005833)^300] / [(1.005833)^300 − 1]
(1.005833)^300 ≈ 5.685
Numerator: 0.005833 × 5.685 ≈ 0.03316
Denominator: 5.685 − 1 = 4.685
M = 700,000 × (0.03316 ÷ 4.685) ≈ 700,000 × 0.007078 ≈ $4,955
The estimated monthly principal and interest payment is approximately $4,955.
Annual debt service: $4,955 × 12 = $59,460
Total payments over 300 months: $4,955 × 300 = $1,486,500
Total interest: $1,486,500 − $700,000 = $786,500
Because the loan term is 10 years and the amortization is 25 years, the loan would not be fully paid off at the end of the term. A balloon balance would remain.
This example is hypothetical and for illustration only. It does not include taxes, insurance, fees, or closing costs. Actual commercial mortgage payments may differ.
Loan Term vs. Amortization Period
These two terms are often confused, but they mean different things.
Loan term is how long the loan remains outstanding before it matures. At the end of the loan term, the remaining balance must be repaid or refinanced.
Amortization period is the period used to calculate the scheduled payments. It determines how the payment is calculated, not necessarily how long the loan lasts.
A commercial mortgage can have a loan term shorter than its amortization period. For example:
- Loan term: 10 years
- Amortization period: 25 years
In this case, the monthly payment is calculated as if the loan would be paid off over 25 years. But because the loan term is only 10 years, the remaining principal becomes due at the end of year 10. That remaining balance is the balloon payment.
This structure is common in commercial real estate. It allows for lower monthly payments while giving the lender an opportunity to renegotiate or require repayment at maturity.
Commercial Mortgage Balloon Payment
A balloon payment is the remaining principal balance due at the end of the loan term when the loan term is shorter than the amortization period.
Using the example above:
- Loan amount: $700,000
- Amortization: 25 years
- Loan term: 10 years
After 10 years of payments, the loan would not be fully paid off. The remaining balance—the balloon—would be due.
The calculator can estimate the remaining balance at the end of the loan term. This helps borrowers plan for refinancing or sale.
Borrowers should not confuse the monthly payment with full repayment of the loan. A low monthly payment based on a long amortization period can still leave a substantial balance due at maturity.
Not every commercial mortgage has a balloon payment. Some loans are fully amortizing over the loan term. Others have interest-only periods or different structures.
Commercial Mortgage LTV Calculation
LTV measures the loan amount relative to the property's value.
LTV = Loan Amount ÷ Property Value × 100
If the property value is $1,000,000 and the loan amount is $700,000:
LTV = $700,000 ÷ $1,000,000 × 100 = 70%
LTV is important because it indicates how much equity the borrower has in the property. A larger down payment lowers the LTV.
Commercial lenders often have their own LTV requirements, which vary by property type, lender, and market conditions. A particular LTV does not guarantee approval. Lenders also consider debt service coverage, credit, property condition, and other factors.
Commercial Mortgage Costs Beyond Principal and Interest
The monthly principal and interest payment is only part of the cost. Commercial property financing may involve:
- Property taxes
- Insurance
- Maintenance
- Association fees
- Lender fees
- Origination charges
- Closing costs
- Appraisal costs
- Legal or professional costs
- Prepayment penalties where applicable
Some calculators include taxes and insurance in the monthly payment. Others only calculate principal and interest. It's important to know which costs are included in the estimate and which are not.
Total project cost should account for these expenses, not just the mortgage payment.
Commercial Mortgage Payment Schedule
A payment schedule—also called an amortization schedule—shows how each payment is applied over the life of the loan.
Each row typically includes:
- Beginning balance
- Scheduled payment
- Principal portion
- Interest portion
- Ending balance
Under a standard amortization structure, early payments contain more interest and less principal. As the loan progresses, the principal portion increases and the interest portion decreases.
For example, in the first year of a 25-year amortization, a larger share of each payment goes to interest. By year 20, most of the payment goes to principal.
The calculator's schedule is based on the entered assumptions. If the loan has a balloon payment, the schedule shows the balance at the end of the loan term. If the rate is variable, the schedule may not reflect future rate changes.
How to Compare Commercial Mortgage Options
Use this checklist when comparing commercial mortgage offers:
- Compare interest rates.
- Compare loan terms.
- Compare amortization periods.
- Check the down payment requirement.
- Review LTV.
- Check annual debt service.
- Review total interest.
- Check whether there is a balloon balance.
- Review lender fees and closing costs.
- Read the complete loan agreement.
No calculator can replace reading the actual loan agreement. The terms that matter most are in the contract.
Frequently Asked Questions
1. What is a commercial mortgage calculator?
A tool that estimates monthly payments, total interest, annual debt service, LTV, and balloon balance for a commercial property loan.
2. How do I calculate a commercial mortgage payment?
Use the amortization formula: M = P × [r(1+r)^n] / [(1+r)^n − 1]. Enter the loan amount, monthly rate, and number of payments.
3. What is the commercial mortgage payment formula?
M = P × [r(1+r)^n] / [(1+r)^n − 1], where P is principal, r is the monthly rate, and n is the number of monthly payments.
4. What is the difference between loan term and amortization?
Loan term is how long the loan lasts before maturity. Amortization is the period used to calculate payments. A loan can have a shorter term than its amortization period.
5. How is commercial mortgage interest calculated?
Interest is calculated on the outstanding principal. For fixed-rate loans, the amortization formula determines how much of each payment goes to interest versus principal.
6. What is a commercial mortgage balloon payment?
The remaining principal balance due at the end of the loan term when the loan term is shorter than the amortization period.
7. How is commercial mortgage LTV calculated?
LTV = Loan Amount ÷ Property Value × 100. A larger down payment lowers LTV.
8. Does a longer amortization period reduce monthly payments?
Yes. A longer amortization spreads the principal over more payments, lowering the monthly payment but increasing total interest.
9. Can a commercial mortgage have a balloon balance?
Yes, if the loan term is shorter than the amortization period. The remaining balance becomes due at maturity.
10. What is annual debt service on a commercial mortgage?
The total of all mortgage payments over one year. It's calculated by multiplying the monthly payment by 12.
11. Can I calculate a commercial property mortgage payment online?
Yes. Online calculators estimate monthly payments, total interest, and payment schedules based on your inputs.
12. Why can my commercial mortgage estimate differ from a lender's quote?
Because lenders apply their own rates, fees, terms, and underwriting. The calculator uses simplified inputs.
13. Does the calculator include property taxes and insurance?
Some do, some don't. Check the calculator's inputs to see which costs are included in the estimate.
14. How much down payment is needed for a commercial mortgage?
It varies by lender, property type, and borrower qualifications. Commercial lenders often require larger down payments than residential lenders.
Related Calculator Topics
If you're evaluating commercial financing, other calculators can help. A commercial loan calculator estimates loan payments. A business loan calculator covers general business financing. A DSCR calculator helps assess debt service coverage. A mortgage calculator estimates residential payments. A loan amortization calculator shows payment breakdowns. A business valuation calculator helps assess property or company value.
Disclaimer
Disclaimer: This article and calculator provide estimates for educational purposes only and are not financial, investment, tax, accounting, or legal advice. Actual commercial mortgage rates, fees, terms, payments, and qualification requirements vary by lender and property.